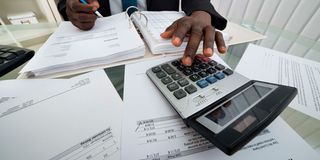
Kenya’s public financial management is on the cusp of a major transformation. For years, the government has operated under cash-basis accounting, a method that only captures transactions when real money is exchanged.
While this system has served its purpose, it has its limitations, particularly as the nation’s financial landscape becomes more complex. Now, in a major reform, Kenya is set to transition to the International Public Sector Accounting Standards (IPSAS) accrual basis—a change that promises to enhance transparency, accountability, and decision-making in public finance.